The monthly scoreboard for August 2026, generated straight from the strategy catalog. Start with the model portfolios, the diversified blends most people should actually hold, then work down to the full board of 93 strategies. Every table carries the month, the year to date and the trailing 1-year return, because the long view is the one that decides whether a strategy is worth holding.
Model portfolios: the blends that matter most
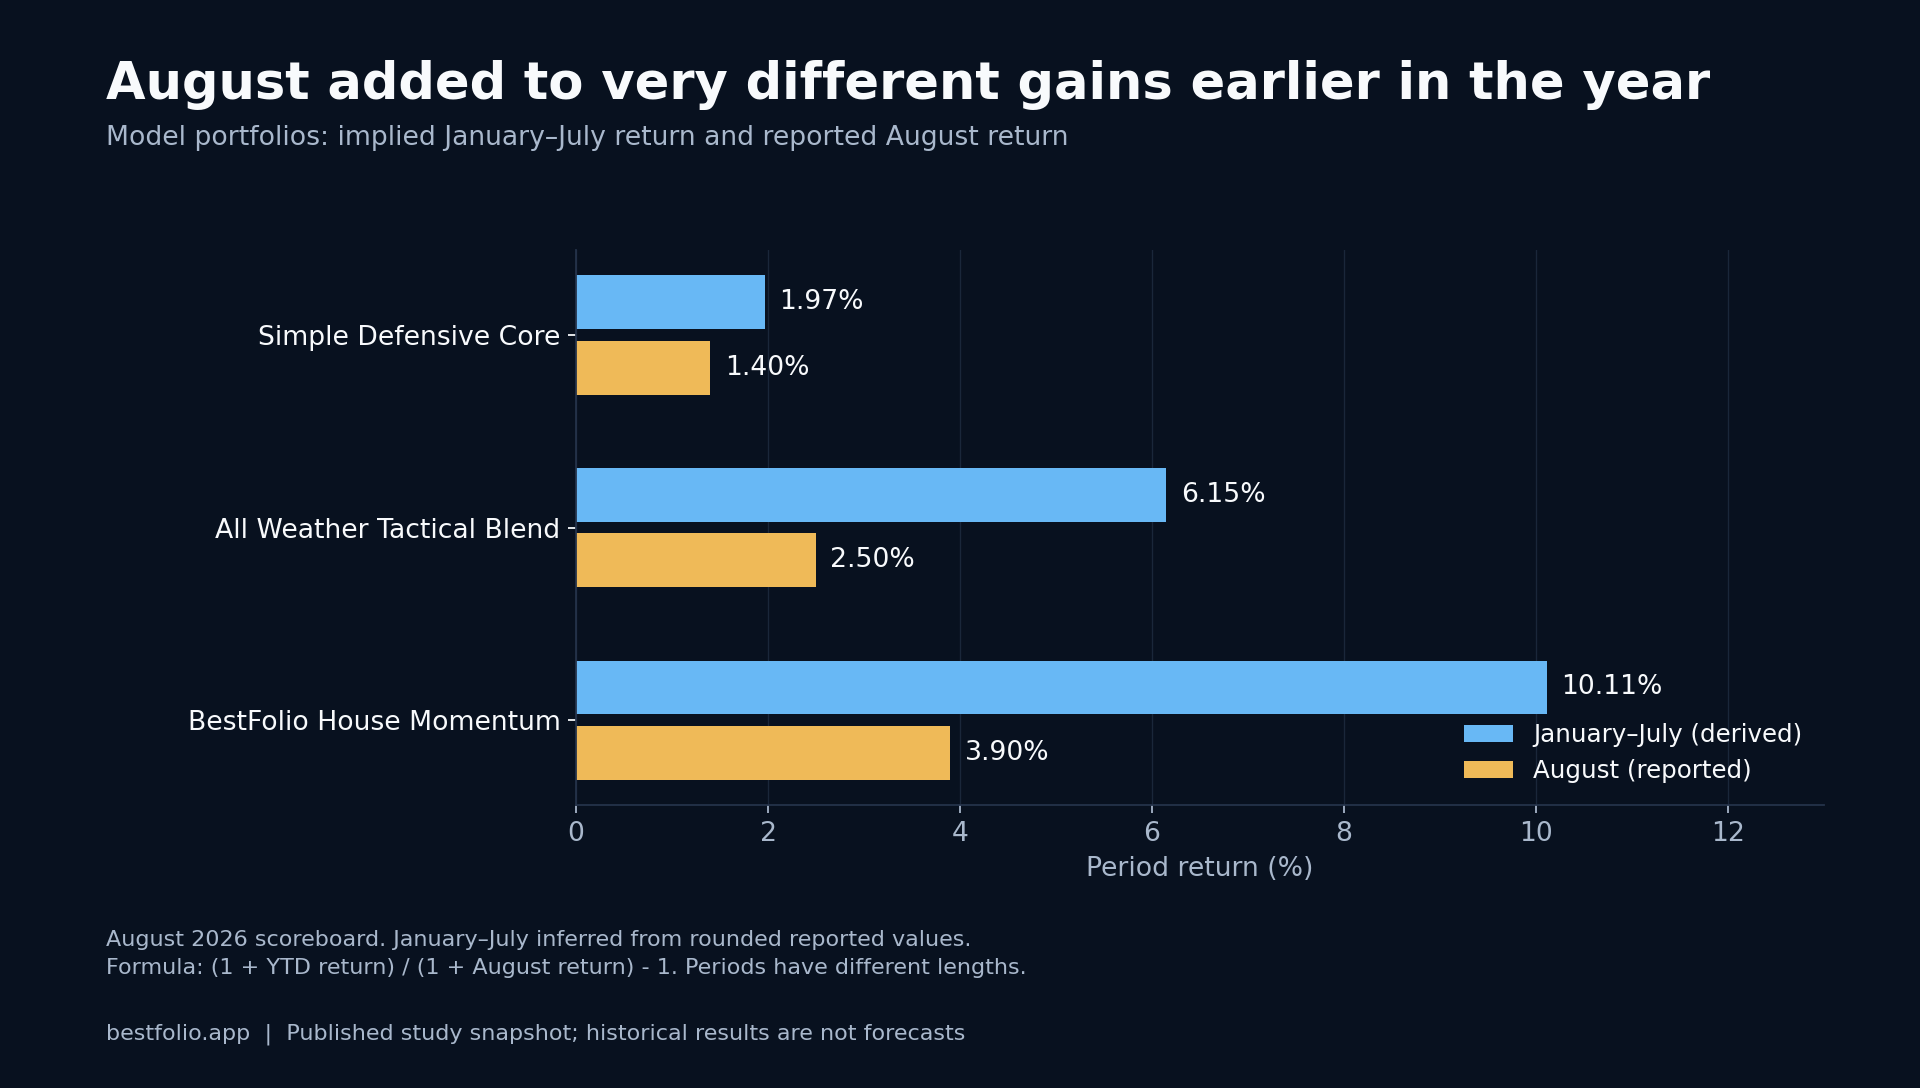
These are the ready-to-clone model portfolios we track, spanning three risk profiles from conservative to aggressive. Each is a blended, multi-strategy allocation from the portfolio library, not a single strategy, so this is the honest read on how a diversified BestFolio investor actually did, over the month, the year, and since inception.
| Model portfolio | Risk | Month | YTD | 1Y | CAGR since inception |
|---|---|---|---|---|---|
| Simple Defensive Core | Conservative | +1.4% | +3.4% | +11.1% | 7.1% |
| All Weather Tactical Blend | Moderate | +2.5% | +8.8% | +16.4% | 10.9% |
| BestFolio House Momentum | Aggressive | +3.9% | +14.4% | +26.7% | 19.3% |
How to read August 2026
Breadth check. Of the 76 strategies on the unlevered board, 34 beat the US market (+2.7%) in August 2026, and 14 are ahead of it year to date. The month itself ran from +9.9% (Gold Cross-Asset Momentum) down to -2.5% (200-Day SMA Trend), a spread of 12.5% in a single month.
Worth noting that Gold Cross-Asset Momentum, the best strategy of August 2026, is not in the year-to-date top five. One month is one data point. The strategies worth holding are the ones that keep compounding over the year and beyond, which is why every table here carries YTD and 1-year, not just the month.
Benchmarks for context: 100% US Stock Market +2.7% for the month (+13.5% YTD, +20.2% 1Y), Classic 60/40 +1.8% for the month (+7.7% YTD, +12.7% 1Y).
Year-to-date leaders
The strategies compounding best so far this year, one row per strategy. This is the table that matters more than the month.
| Strategy | Variant | Month | YTD | 1Y |
|---|---|---|---|---|
| Growth-Inflation Sector Timing | Growth-Inflation Concentrated | +7.4% | +29.4% | +31.4% |
| Inflation Compass | Inflation Compass Standard | +6.4% | +23.0% | +15.9% |
| Mama Bear Portfolio | Mama Bear Standard | +2.8% | +22.7% | +31.3% |
| Sector Rotation (Faber QTAA-Sectors) | Top-3 No Filter | +6.4% | +20.4% | +23.2% |
| Momentum-Correlation Triplet | Triplet Standard | +3.9% | +18.1% | +33.5% |
| Robust Asset Allocation | Robust AA Aggressive | +3.9% | +17.4% | +26.4% |
| PAA (Protective Asset Allocation) | PAA Dynamic Protection | +1.8% | +17.1% | +28.7% |
| GEM (Global Equities Momentum) | GEM Standard | +2.9% | +16.6% | +26.8% |
| GPM (Generalized Protective Momentum) | GPM Standard | +1.0% | +16.3% | +29.5% |
| Carlson's Adaptive 60/40 | Adaptive 60/40 Standard | +4.2% | +15.6% | +31.3% |
Top 10 unlevered strategies in August 2026
The month's leaders, for the record. Read them next to the YTD and 1-year columns before reading too much into a single month.
| Strategy | Variant | Month | YTD | 1Y |
|---|---|---|---|---|
| Gold Cross-Asset Momentum | Gold Cross-Asset (GLD+IEF) | +9.9% | +3.1% | +28.4% |
| Growth-Inflation Sector Timing | Growth-Inflation Concentrated | +7.4% | +29.4% | +31.4% |
| ADM (Accelerating Dual Momentum) | ADM SmartStack (Gold+MF) | +6.5% | +7.6% | +15.8% |
| Sector Rotation (Faber QTAA-Sectors) | Top-3 No Filter | +6.4% | +20.4% | +23.2% |
| Inflation Compass | Inflation Compass Standard | +6.4% | +23.0% | +15.9% |
| 4-3-2-1 Dragon | 4-3-2-1 Capital Efficient | +5.4% | +10.8% | +24.2% |
| EAA (Elastic Asset Allocation) | EAA Golden Offensive | +5.1% | +10.0% | +28.4% |
| Diversified Dual Momentum | Diversified DM Standard | +4.9% | +14.7% | +25.5% |
| Dynamic Macro Allocation (Sadek) | Dynamic Macro Allocation (Sadek) | +4.8% | +12.8% | +27.9% |
| KISS Momentum | KISS 70/30 SmartLeverage | +4.7% | +10.7% | +24.6% |
Leveraged corner
Leveraged variants, ranked separately because raw monthly moves at 2x or 3x are not comparable to the unlevered list. The 1-year column is where their real risk and reward shows up.
| Strategy | Variant | Month | YTD | 1Y |
|---|---|---|---|---|
| VIX Shield | VIX Shield Leveraged | +11.4% | +17.5% | +35.1% |
| TQQQ/QQQ 200MA Band (+4%/-3%) | TQQQ/QQQ Band (Standard) | +11.3% | +10.5% | +30.7% |
| Low Initiative LETF V2 (Dual SMA + TIP) | Low Initiative LETF V2 (Standard) | +8.8% | +18.2% | +41.7% |
| A-RVol Shifter | RVol Shifter, Wongkok 200SMA | +8.2% | -9.3% | +13.5% |
| TQQQ Quadrant Stack | TQQQ Quadrant Stack Standard | +8.2% | +7.3% | +24.2% |
Weakest 5 of the month
| Strategy | Variant | Month | YTD | 1Y |
|---|---|---|---|---|
| 200-Day SMA Trend | VNQ 200-Day Trend | -2.5% | +2.4% | -0.0% |
| Stoken's ACA - Daily [Dynamic Bond] | ACA REIT Sleeve (VNQ/IEF) | -2.5% | +11.1% | +8.6% |
| Alpha-One Momentum | Alpha-One Momentum (Standard) | -2.0% | -1.2% | +6.3% |
| VAA (Vigilant Asset Allocation) | VAA-G4 SmartStack (Gold+MF) | -0.1% | +3.3% | +20.8% |
| KDA (Kipnis Defensive Adaptive) | KDA Top 4 | +0.1% | +8.5% | +21.0% |
Methodology: strategy returns come from each strategy's published NAV series, the same out-of-sample track records shown on the leaderboard. Model portfolio returns use the same blended NAV shown on each portfolio's library page, measured through the last trading day of the month. One month is one data point; the strategy and portfolio pages show full multi-decade histories, drawdowns, and walk-forward results. This post is generated automatically from the database on the first of each month.
Educational information only, not investment advice. Past performance does not guarantee future results.