Five strategies go live on August 25, bringing the public catalog to 93 published strategies, 72 of them tactical. All five are Pro; the free tier is unchanged. The batch also ships a leveraged variant with the strongest risk label we have put on any strategy page. One thread connects these releases: inflation-regime rotation was the scenario the catalog handled least well, and this batch addresses that directly.
Inflation Compass
David Varadi's Inflation Compass leads the batch, and it is the cleanest mechanism I have seen for inflation-regime rotation: one sector position at a time, refreshed monthly, determined by two independent regime reads. The growth signal comes from SPY's 200-day moving average. The inflation signal uses the bond market's 5-year breakeven rate, confirmed by a sector ratio, so it reflects what the market is currently pricing rather than what last month's CPI report said.
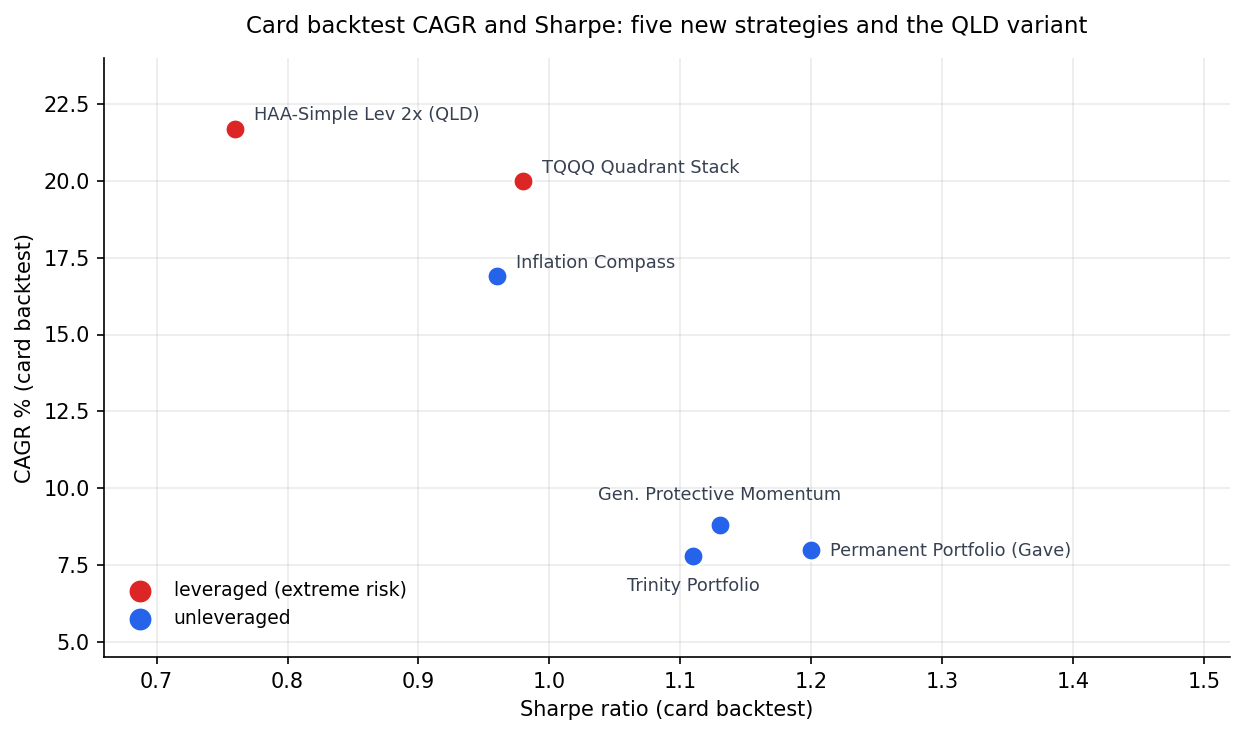
Each of the four quadrants maps to a specific sector, and the strategy holds only that sector for the month. The card runs on data back to 1950 and, after the 13-month warmup, its backtest starts in February 1951, covering every postwar inflation episode. Because live ETFs did not exist for most of that period, the deep-history portion runs on index and mutual-fund proxy chains, as it does for all long-window strategies in the catalog. The result across that full window is 17.3% CAGR with a Sharpe ratio of 0.98.
Inflation Compass succeeds Growth-Inflation Sector Timing in the catalog; that strategy stays published with a cross-link between the two pages.
TQQQ Quadrant Stack
TQQQ Quadrant Stack is the first strategy in the catalog credited to a Reddit username. It was designed by u/Separate-Ad-9633 in r/LETFs, and the card carries that attribution. The structure pairs a 30% TQQQ sleeve with ZROZ, international small-cap value, and return-stacked diversifiers. SPY and TLT trend breaks each gate their respective sleeve, routing into gold and managed futures when conditions deteriorate. Half the book (the diversifier side) never trades. The card result is 18.6% CAGR with a Sharpe of 0.91.
It loses money to monthly whipsaw. In years where both trend signals change direction frequently within short windows, the strategy takes losses from multiple sides at once. The clearest examples in the backtest are 2018 and 2022. That cost is visible in the detailed results and worth understanding before sizing the strategy in a live portfolio.
Three Classics for the Core
Three well-established strategies round out the batch as ballast and blend material rather than return engines. GPM (Generalized Protective Momentum, by Keller and Keuning) delivers 9.2% CAGR with a Sharpe of 1.13. Meb Faber's Trinity Portfolio runs at 7.7% CAGR with a Sharpe of 1.06. Charles Gave's Permanent Portfolio (Gave) posts 7.9% CAGR and the highest Sharpe of the three at 1.17. These are not return maximizers. Their value lies in what they do not cost during periods when higher-octane strategies draw down hard.
HAA-Simple Leveraged 2x (QLD)
HAA-Simple Leveraged 2x (QLD) ships as a variant of HAA, added by subscriber request. The performance history is notable: 23.5% CAGR and a Sharpe of 0.81 across the full backtest window. The risk history must be read alongside it.
The dot-com unwind produced a drawdown of roughly -83% on daily prices, and the strategy took 9.9 years to recover. A second deep episode runs from 1983 into early 1988. These are not theoretical tail risks; they represent what the strategy has actually done under severe stress. The history is brutal, and I would rather lose a signup than hide it. The strategy page flags this as extreme risk and states plainly that it is not investable on its own. It belongs only inside a broader portfolio where a volatile position can be properly sized and where a holder has genuinely thought through what staying underwater for that long means in practice.
Live for the September Rebalance
All five strategies, plus the QLD variant, are live today with full backtests and current signals, in time for the September rebalance. Signals publish on the first trading day of September. All are Pro.
The full release:
| Strategy | CAGR | Sharpe |
|---|---|---|
| Inflation Compass | 17.3% | 0.98 |
| TQQQ Quadrant Stack | 18.6% | 0.91 |
| GPM | 9.2% | 1.13 |
| Trinity Portfolio | 7.7% | 1.06 |
| Permanent Portfolio (Gave) | 7.9% | 1.17 |
| HAA (QLD variant) | 23.5% | 0.81 |
Past performance does not guarantee future results. Backtested results are hypothetical and do not represent actual trading.