WALK-FORWARD VALIDATION
Find out if a strategy mix held up when its weights were set in real time.
Pick a set of strategies and BestFolio re-fits their weights every month using only the months before it, then records what those weights earned next. The weights are out of sample. The choice of strategies is not: you pick them knowing how they did, and several were published after the test window starts.
Already a Pro subscriber? Open the live tool →
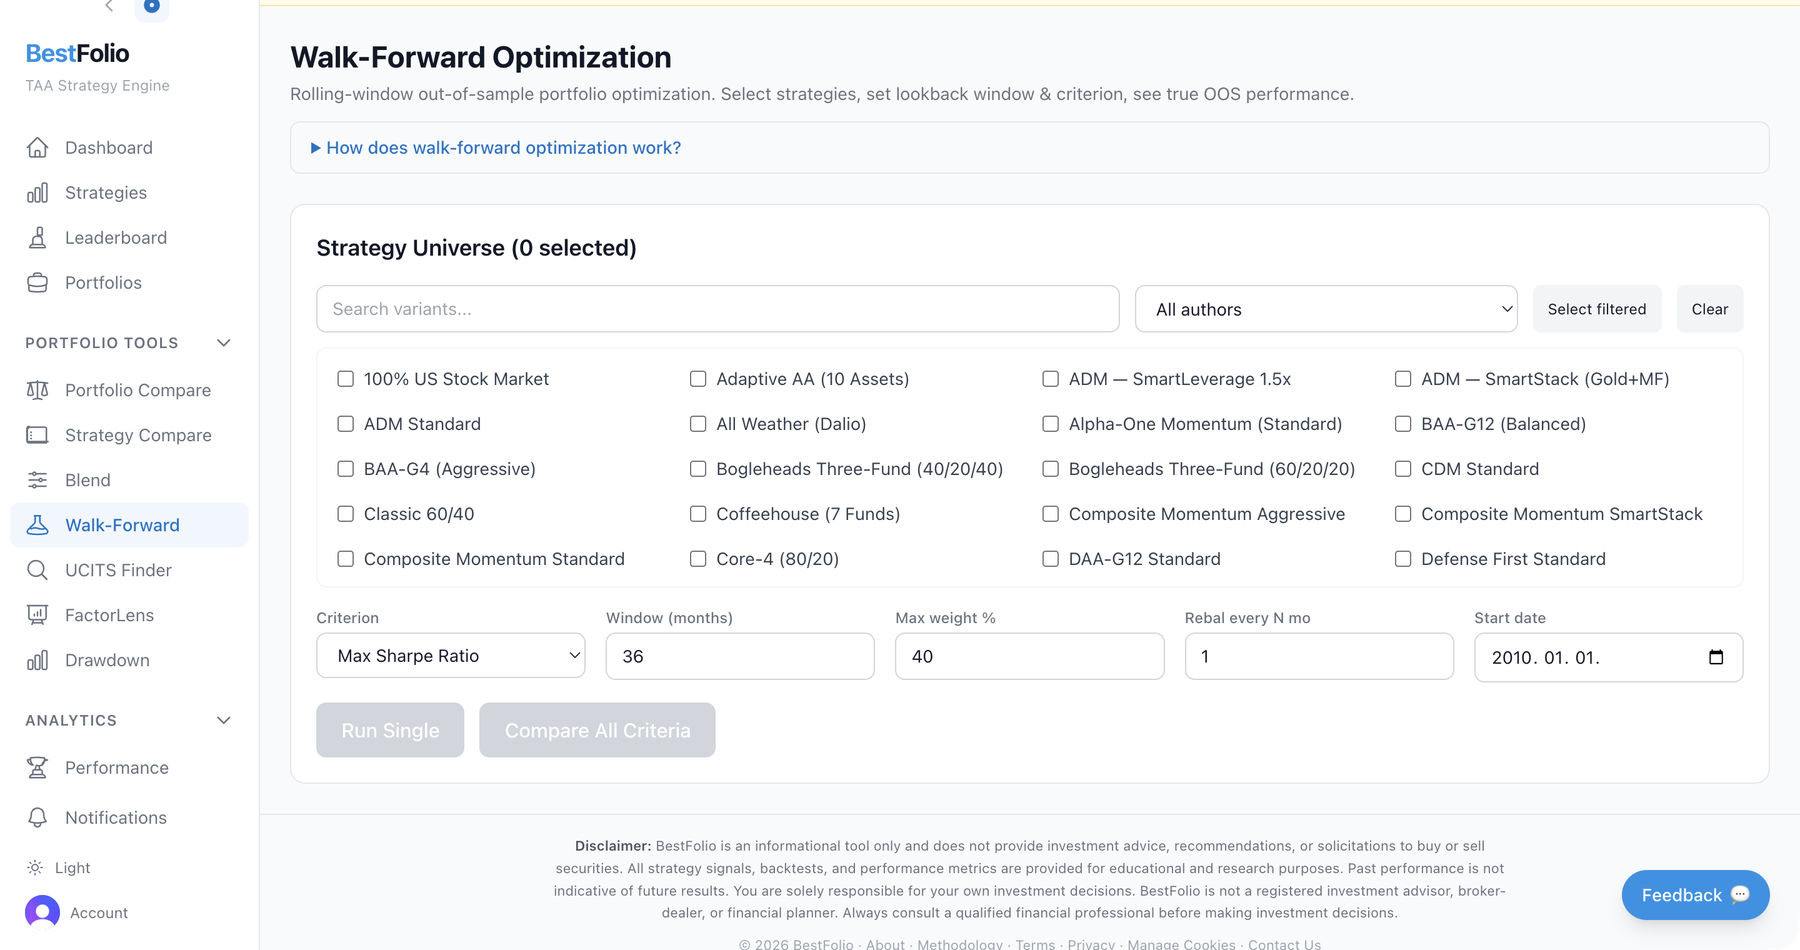
BestFolio walk-forward optimization tool: select strategies, set the lookback window and optimization criterion, and run a rolling walk-forward of the portfolio weights.
- Out-of-sample weights
- Weights are fitted on a trailing window (36 months by default), applied to the next month, then the window rolls forward one month.
- Pools of 2 to 12 strategies
- The optimizer weights a pool you choose; 5 to 8 strategies with different mechanisms works best.
- Configurable windows
- Adjust the lookback window, the weight cap per strategy and the rebalance frequency. Defaults: 36 months, 40%, monthly.
What it is
Walk-forward validation fits a choice on a training window and tests it on the period right after, which the fit never saw. In a BestFolio walk-forward portfolio the only thing fitted is the weights: each month the optimizer finds the weights that best met the chosen criterion over the trailing window, applies them to the next month, then rolls the window forward. The result shows what the weighting would have done if it had been chosen in real time. It is not an out-of-sample test of the strategies themselves: their rules were fixed in advance, several were designed or published after the test window starts, and the pool is chosen with hindsight.
Free vs Pro
Free
- ✓Browse the published walk-forward templates in the Library
- ✓Each template's equity curve, drawdown and headline metrics
- ✓Read how the method works before you upgrade
Pro
- ✓Run your own walk-forward in the walk-forward tool
- ✓Pools of 2 to 12 strategies from all 111+ in the catalog
- ✓Save walk-forward portfolios and follow their monthly weights
- ✓Configurable window, weight cap and rebalance frequency
- ✓Per-strategy contribution analysis on portfolio walkforward
- ✓Worst-case window highlight (sequence-risk view)
Strategies that use this
HAA (Hybrid Asset Allocation)
Keller hybrid; recession-aware tactical.
View strategy →
GEM (Global Equities Momentum)
Antonacci dual momentum; absolute + relative.
View strategy →
BAA (Bold Asset Allocation)
Keller canary-based regime detection.
View strategy →
VAA (Vigilant Asset Allocation)
Keller offensive / defensive switching.
View strategy →
DAA (Defensive Asset Allocation)
Keller defensive variant of VAA.
View strategy →
ADM (Accelerated Dual Momentum)
Antonacci accelerated; faster signal.
View strategy →
Frequently asked questions
What is walk-forward validation in plain English?+
It checks whether a choice that looks good with hindsight still works when it has to be made in real time. Here the choice is the portfolio weights: each month they are fitted on past data only, then tested on the next month, which the optimizer has not seen. If the weights only worked when fitted to the whole history, the walk-forward shows it. It does not test the strategies' own rules, which were fixed before the run.
How does walk-forward differ from a regular backtest?+
A regular backtest of a blend holds one set of weights over the whole history, often picked after looking at that history. A walk-forward re-fits the weights each month from past data only, so the weighting has no look-ahead. The strategies inside the pool are the same backtests in both cases, so a walk-forward removes none of the hindsight in how they were designed or chosen.
Does walk-forward eliminate overfitting?+
No. It removes look-ahead from the weights only. The strategies were designed by their authors, several after the start of the test window, and you pick the pool today knowing how each one did. Read a walk-forward result as how well the weighting method coped with a pool chosen with hindsight, not as decades of out-of-sample proof for the strategies.
Which BestFolio strategies can go into a walk-forward?+
Walk-forward weights a pool of strategies, so it runs on a set of 2 to 12 strategies rather than on one. Any published strategy can be part of the pool, including the free ones (HAA, GEM, Permanent Portfolio, Classic 60/40, Golden Butterfly and RP Gold+SCV), and every pool runs on the same engine.
Is walk-forward a free or Pro feature?+
Running a walk-forward is a Pro feature, including on the free strategies, and so is saving a walk-forward portfolio. Without Pro you can browse the published walk-forward templates in the Library, with their equity curves and metrics.
Start free, upgrade when you need it
6 strategies free forever. Upgrade to Pro for the full library, walk-forward, blending, and monthly signals.
14-day money-back guarantee on your first payment. Refund terms and statutory rights.