This release has a theme, and the theme is momentum. Five strategies, all built on the same simple observation: assets that have been going up tend to keep going up for a while, and assets that roll over tend to keep rolling. That idea is one of the most studied effects in finance. What separates these five is the implementation: which lookback you trust, how many things you hold, what you do when two winners move together, and when you bail to cash.
Three of the five are BestFolio Research originals. One comes from Quantpedia's research team, and one is a peer-reviewed model from a 2022 SSRN paper. We backtested all of them with our standard fallback chain: real ETF data where it exists, careful proxies (mutual funds, indices, academic factor series) before that. One we ran all the way back to 1928, which is the part I am most excited about. Start there.
1. Century Momentum
BestFolio Research. Tactical, aggressive. Backtested to 1928.
Here is the whole rule. Hold a top-decile US momentum sleeve while it sits above its 10-month moving average. The month it closes below, sell it and sit in 10-year Treasuries until the trend turns back up. That is it. One risk asset, one safe asset, one trend switch checked once a month.
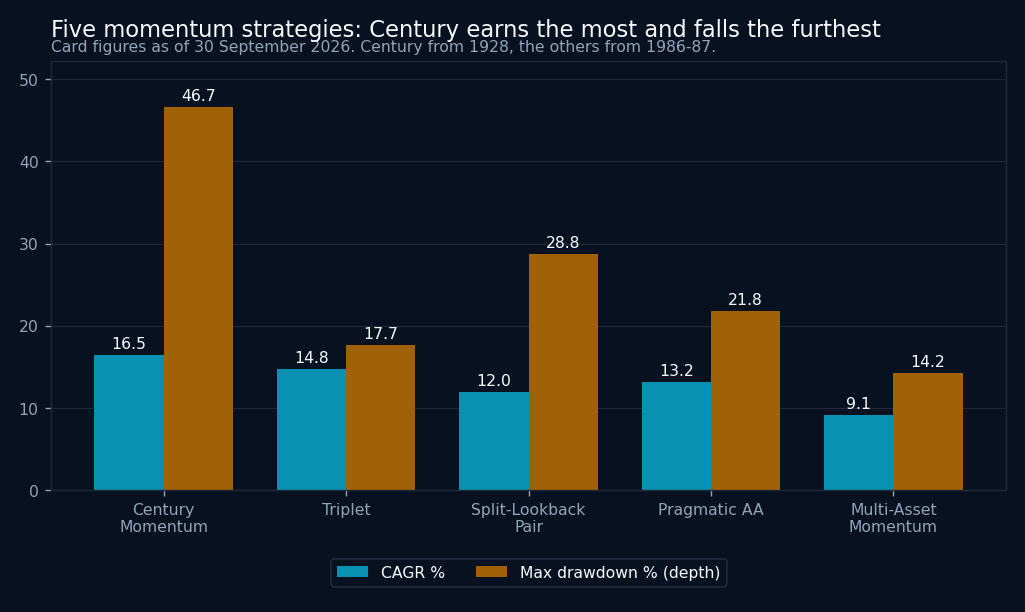
What makes it interesting is the history. Live, the momentum sleeve is SPMO. For the decades before momentum ETFs existed, we use the Fama-French top-decile momentum portfolio, which goes back to 1927. So we can actually watch this rule walk through 1929, the 1937 relapse, the 1973-74 stagflation bear, 2000, and 2008. Over 98 years it compounded at roughly 16.5% a year.
It is also the most aggressive thing in the batch, and I want to be honest about that. The trend filter cuts the worst of the crashes, but a single momentum sleeve still took a drawdown near 47% at its worst. The 10-month filter is slow on purpose, so it gives back a chunk before it gets you out. If a 47% paper loss would make you sell at the bottom, this is not the one to run by itself. Held as a high-octane sleeve next to calmer strategies, it earns its place. See it at Century Momentum.
2. Momentum-Correlation Triplet
BestFolio Research. Tactical, moderate.
This one starts where most momentum strategies stop. It scores 14 global assets on a blended 3, 6, and 12-month momentum signal and takes the 5 leaders. Then it does the extra step: out of those 5, it keeps only the 3 that are least correlated to each other over the last year. Equal weight, with a cash filter so a leader with negative absolute momentum drops out.
The point is to stop momentum from quietly handing you the same bet three times. In a strong equity run, the top 5 might be the S&P, the Nasdaq, and three things that move with them. The correlation screen throws two of those overboard and forces in something that zigs when they zag. Over the full backtest it ran a Sharpe around 0.95 with a worst drawdown of about 18%, which is the kind of ratio you get from picking winners that genuinely diversify. Momentum-Correlation Triplet.
3. Split-Lookback Momentum Pair
BestFolio Research. Tactical, moderate.
Every momentum strategy has to pick a lookback, and the pick matters more than people admit. A 12-month signal is steady but slow to react. A 1 to 3-month signal is quick but whippy. Backtests love whichever one happened to fit the period you tested.
So this strategy refuses to choose. It splits capital into two halves. One half runs a slow 12-month signal, the other runs a fast blend of 1, 3, and 6-month momentum. Each half independently picks one winner from the same 6-asset menu (three equity funds, gold, long Treasuries and TIPS, with cash as the fallback), and you hold both picks. When the fast and slow clocks agree, you are concentrated. When they disagree, you are hedged across two timeframes by construction. It is a bumpier ride than the Triplet, around 12% a year since 1985, and it is the cleanest example in the batch of diversifying a decision instead of an asset. Split-Lookback Momentum Pair.
4. Pragmatic Asset Allocation
Radovan Vojtko et al. (Quantpedia). Tactical, moderate.
The Quantpedia team built this as a no-nonsense multi-asset momentum model, and the name fits. Rank 7 diversified ETFs by composite momentum (an average of the 1, 3, 6 and 12-month returns), hold the top 3 equal weight, and send any slot with negative momentum to cash. Rebalance monthly. Nothing exotic.
What you get for that simplicity is a strong all-weather record: roughly 13.8% a year with a Sharpe near 0.91 and a worst drawdown around 21%. It is a good anchor strategy, the one you run as a core while the spicier momentum sleeves orbit around it. Pragmatic Asset Allocation.
5. Multi-Asset Momentum
Zambrano & Rizzolo (Vitral Advisors), SSRN 4199648. Tactical, moderate.
This is the most engineered of the five, and it goes straight at the lookback problem the Split-Pair only sidesteps. Instead of one momentum measure it computes 9: three momentum definitions across three lookbacks, then aggregates them into one score. The idea from the paper is that no single specification is reliably best, so averaging across them cuts the risk of overfitting any one. It also marks down assets that are too correlated with the rest of the book and keeps a protective cash fraction.
From a 13-asset universe it holds the top 5 equal weight. The result is a Sharpe around 0.89, a little below the Triplet's 0.95, and the shallowest worst drawdown in the batch, about 15%. Lower headline return than Pragmatic AA, about 10% a year, but the smoothest path of the five. There are three variants on the page (Standard, Low Protection, Ensemble) if you want to trade some of that smoothness for return. Multi-Asset Momentum.
The five side by side
Here are the five as their strategy pages show them on 27 October 2026. Each runs over its own full history, so the start years differ.
| Strategy | Backtest from | CAGR | Worst drawdown | Sharpe |
|---|---|---|---|---|
| Century Momentum | 1928 | 16.5% | -46.8% | 0.76 |
| Momentum-Correlation Triplet | 1987 | 14.4% | -17.7% | 0.95 |
| Split-Lookback Momentum Pair | 1985 | 12.1% | -28.8% | 0.66 |
| Pragmatic Asset Allocation | 1985 | 13.8% | -20.9% | 0.91 |
| Multi-Asset Momentum | 1985 | 9.9% | -15.2% | 0.89 |
How they fit together
You would not run all five at full size. They are momentum strategies, so in a roaring trend they will overlap, and in a sharp reversal they will all take a hit in the same month before the trend filters react. Momentum is one factor, and these are five expressions of it.
The blends I like pair the calm anchors with the aggressive sleeve. Multi-Asset Momentum or Pragmatic AA as the core, a slice of the Triplet for its correlation discipline, and a small position in Century Momentum for the high-octane tail. The Blend tool will show you the combined drawdown and Sharpe for any mix you put together, which is the honest way to size the aggressive one: see what 10% of Century does to the whole portfolio's worst year before you commit to it.
All five are live now, and all are Pro. If you want to run your own numbers through them, the backtests and the blend builder are the reason to be on the paid plan. See pricing.
One note on the numbers. Figures were updated on 18 October 2026 and move as the backtests extend. Every figure here is a full-period backtest with our documented proxy chains, not a live track record. Pre-ETF history leans on mutual funds and academic factor series, and we list the exact chain on each strategy page. Past backtests are not future returns, momentum included.