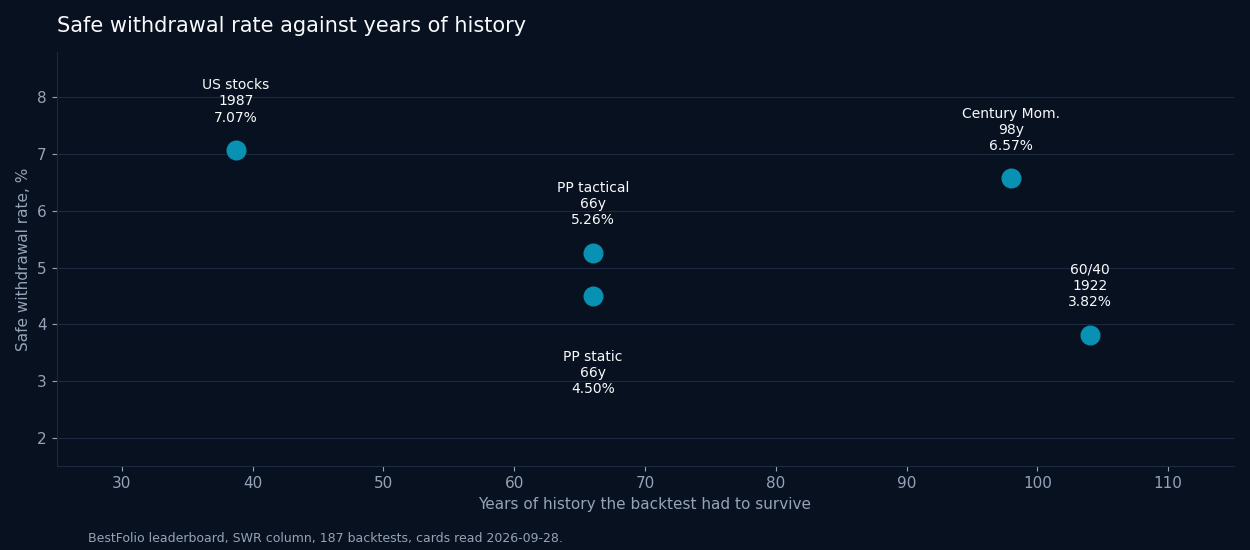
Note (28 September 2026): this May study predates our current withdrawal-rate method and later data corrections, and its headline no longer holds. On today's strategy pages several strategies fall below 4%: the classic 60/40 at 3.82%, Buy the Dip at 3.64%, Paired Switching at 2.81% and UIS at 2.29%. Each strategy page carries the current safe withdrawal rate, and our later post on tactical strategy withdrawal rates uses the current method.
Correction, 8 October 2026: the results table and every strategy figure in the text were restated from each strategy's current card (runs of 5 October 2026). Most cards now reach back further than in May (the classic 60/40 to 1922, HAA to 1974, VAA-G4 to 1977), so several figures and the ranking moved. HAA Leveraged 2x was shown at 23.3% a year with a -34.2% maximum drawdown; its card now shows 26.4% and -36.5%, so the old drawdown understated the risk. VAA-G4 SmartStack's withdrawal rate is now 11.5% (was 15.3%), HAA SmartStack's 9.7% (was 14.2%) and the classic 60/40's 3.8% on a history that includes the Depression (was 6.7%). The sentences that drew conclusions from the old figures were updated to match. The title also changed: it said 'Why 50+ TAA Strategies All Beat the 4% Rule', which no longer holds.
Correction, 13 October 2026: the synthetic history of GDE before its March 2022 launch now matches the fund's 90/90 exposure (90% S&P 500 and 90% gold futures), so the Quartet row now shows its rerun card: 11.4% CAGR, a -27.9% maximum drawdown, a 0.96 Sharpe and a 7.3% PWR (was 11.5%, -28.9%, 0.95 and 7.4%). Its 8.2% SWR and its place in the table are unchanged.
Correction, 15 October 2026: the managed-futures history before KMLM now uses the BTOP 50 index (and DBMF from 2019), so the five strategies in the table that hold managed futures were rerun. VAA-G4 SmartStack now sustains 11.8% (was 11.5%) with a -18.8% maximum drawdown (was -19.8%), and its deepest drawdown is now the one of 2026, not 2015 to 2016. HAA SmartStack keeps its 9.7% withdrawal rate and the Quartet its 8.2%; ADM SmartStack moves to 8.2% (was 8.1%) and the 4-3-2-1 Leveraged to 8.0% (was 7.9%).
Correction, 16 October 2026: early-1990s international and emerging-market history now uses index data instead of two actively managed funds, so the ten TAA rows and the Bogleheads Three-Fund were rerun. ADM moves most: ADM Standard now sustains 7.3% (was 9.2%) with a 14.8% CAGR (was 15.8%), and ADM SmartStack 6.6% (was 8.2%) with a 15.4% CAGR and a -24.7% maximum drawdown (was 16.2% and -24.1%), so both move down the table. BAA-G4 now sustains 12.7% (was 13.4%), HAA SmartStack 9.9% (was 9.7%) and VAA-G4 SmartStack 11.7% (was 11.8%).
Correction, 18 October 2026: figures updated to the current cards. Sharpe is now measured above cash, see the changelog, so every Sharpe in the table and the text is lower (HAA Standard 1.10, was 1.50); CAGR, drawdowns and withdrawal rates did not move with that change. HAA Standard now shows a 16.4% CAGR and a 9.9% PWR, and the HAA SmartStack figures in the text now match its row (9.8% SWR, -22.7% maximum drawdown).
The 4% rule is the most-cited number in retail retirement planning. William Bengen published it in 1994. SAFEMAX of 4% real for a 60/40 portfolio, 30-year horizon, every single starting year from 1926 to 1976. Withdraw 4% in year one, adjust the dollar amount upward by inflation each year, and you'd never run out across any window in 66 years of US data.
Bengen has since updated the framework substantially in his 2025 book A Richer Retirement and the templates at bengenfs.com. Under the modern formulation, 4% is the recommendation for 50-year FIRE horizons specifically, while traditional 30-year retirement supports closer to 4.7% on a multi-cap rising-glidepath portfolio rather than static 60/40. The 4% folk wisdom is still right, just for a more specific use case than most people quote it. We treat both numbers as relevant benchmarks below depending on the planning horizon.
The other question almost nobody asks: what happens if I don't hold 60/40 (or the rising glidepath) at all? What if I hold a TAA strategy that rotates defensively when the canary flips? What if I hold a capital-efficient stack with built-in diversification?
We computed the rolling-window safe withdrawal rate (SWR) and perpetual withdrawal rate (PWR) for every published strategy in the BestFolio catalog using the same Bengen-style methodology. In May 2026 that meant 51 strategies and 80 variants. Real US CPI inflation from FRED. The results are not subtle: in May every single published strategy cleared Bengen's 4% benchmark, and on today's cards the best unleveraged TAA strategies sustain withdrawal rates above 11%.
The headline matters less than understanding why, and where the number stops being useful. The rest of this post is the methodology, the table, the mechanism that makes TAA strategies more withdrawal-resilient than static portfolios, and the four honest reasons you should still anchor your retirement plan closer to Bengen's number than to ours.
The methodology
We use the same approach Bengen used in 1994, with three differences: we run it on actual strategy NAVs (not just 60/40), we use FRED's CPI-U for inflation (not Bengen's older inflation series), and we run it programmatically across every strategy variant rather than picking one.
The algorithm:
- Take the strategy's monthly NAV series since inception (capped at the data window the backtest engine has built up).
- Choose the rolling-window length: 30 years if the backtest covers at least 30 years, else 20 years, else 10 years.
- For each rolling N-year window starting at every available month, simulate withdrawing a fixed real dollar amount monthly (inflation-adjusted via FRED CPI for that window).
- Binary-search for the maximum withdrawal rate where the portfolio survives every single window without going to zero.
That's the SWR. The PWR (perpetual withdrawal rate) is the stricter version: the maximum rate where the portfolio's ending real balance is at least the starting balance in every window. SWR keeps you alive; PWR preserves capital for heirs.
When we first ran this in May 2026, the data window for most strategies started somewhere between 1986 and 1992 (the earliest common inception date across the underlying assets), giving us 33 to 37 years of NAV history, all post-1990. The cards have since been extended back with older proxy data: in the table below half the histories start in 1985 and the other half reach further back (HAA to 1974, VAA-G4 to 1977, the classic 60/40 to 1922). A 30-year rolling window still leaves plenty of overlapping windows per strategy.
The "post-1990" detail is the load-bearing caveat. We will come back to it.
The headline result
Sorted by SWR, top to bottom for a representative cut of the catalog. All numbers are real outputs of the BestFolio backtest engine on production data, restated on 8 October 2026 from each strategy's current card (the Quartet row on 13 October 2026, the five rows that hold managed futures on 15 October 2026, and the rows that hold international or emerging-market stocks on 16 October 2026; the Sharpe column, now measured above cash, on 18 October 2026). History from is the first year of each card's backtest.
| Strategy variant | Type | History from | CAGR | Max DD | Sharpe | SWR | PWR |
|---|---|---|---|---|---|---|---|
| HAA Leveraged 2x | TAA (leveraged) | 1974 | 26.5% | -36.5% | 1.04 | 14.2% | 14.1% |
| BAA-G4 (Aggressive) | TAA (unleveraged) | 1985 | 17.1% | -29.1% | 0.95 | 12.7% | 12.4% |
| HAA SmartLeverage 1.5x | TAA (leveraged) | 1974 | 21.2% | -27.9% | 1.03 | 12.2% | 12.0% |
| VAA-G4 Standard | TAA (unleveraged) | 1977 | 16.0% | -20.9% | 0.92 | 11.9% | 10.9% |
| VAA-G4 SmartStack (Gold+MF) | TAA (stacked, above 1x) | 1977 | 18.7% | -18.8% | 0.93 | 11.7% | 11.1% |
| HAA Standard | TAA (unleveraged) | 1974 | 16.4% | -19.5% | 1.10 | 10.4% | 9.9% |
| HAA SmartStack (Gold+MF) | TAA (stacked, above 1x) | 1974 | 18.4% | -22.7% | 1.05 | 9.8% | 9.4% |
| GEM Standard | TAA (unleveraged) | 1985 | 14.2% | -33.7% | 0.85 | 9.5% | 8.9% |
| 4-3-2-1 Leveraged | Static (leveraged) | 1985 | 13.5% | -33.9% | 0.75 | 8.0% | 7.3% |
| Quartet 20/20/30/30 (NTSX/GDE/RSST/ZROZ) | Static | 1985 | 13.0% | -27.9% | 0.77 | 7.8% | 7.1% |
| ADM Standard | TAA (unleveraged) | 1985 | 15.7% | -25.8% | 0.85 | 7.2% | 6.9% |
| Cockroach (5x20%) | Static | 1985 | 10.2% | -21.8% | 0.81 | 6.7% | 5.5% |
| Bogleheads Three-Fund | Static | 1985 | 9.3% | -35.5% | 0.64 | 6.2% | 4.6% |
| ADM SmartStack (Gold+MF) | TAA (stacked, above 1x) | 1985 | 15.9% | -28.3% | 0.82 | 6.1% | 5.8% |
| Golden Butterfly | Static | 1985 | 8.8% | -19.3% | 0.73 | 6.1% | 4.8% |
| Permanent Portfolio (Static) | Static | 1976 | 8.5% | -20.2% | 0.56 | 5.4% | 3.9% |
| All Weather (Dalio) | Static | 1971 | 8.4% | -22.1% | 0.51 | 4.4% | 3.1% |
| Classic 60/40 | Static | 1922 | 8.7% | -63.2% | 0.50 | 3.8% | 2.5% |
The number that should jump out: VAA-G4 SmartStack sustains an 11.7% real withdrawal rate with a maximum drawdown of -18.8%. That's nearly 3x Bengen's 4% rule, with shallower drawdowns than the Classic 60/40 (-63.2%) or the Bogleheads Three-Fund (-35.5%). Same methodology, completely different outcome.
Bengen's own canonical 60/40 portfolio showed up at 6.7% SWR in our May run, on a history that started at the end of 1988. Its card now starts in 1922, so its windows include the Depression, and it comes out at 3.8%, close to Bengen's 4%. The years since the late 1980s have been kind to bonds and gold. Read on for why that matters.
Where Bengen still wins (the honest caveats)
Five reasons you should not actually withdraw 11.7% from your VAA-G4 SmartStack portfolio.
1. Horizon matters. Our 30-year SWR is too high for 50-year FIRE planning.
The numbers in the table above are rolling 30-year SWRs, computed the same way Bengen's original 1994 paper did. That's the right benchmark if you're planning a traditional retirement starting in your 60s. It's not the right benchmark if you're FIRE planning at 35 with a 50-year horizon ahead.
The relationship between horizon and SWR is non-linear and unfriendly. More years of inflation-adjusted withdrawals means more sequence-of-returns risk to survive, and the SWR drops accordingly. Bengen's own updated work puts the 30-year horizon on a multi-cap rising-glidepath at roughly 4.7% and the 50-year FIRE horizon at the more familiar 4%. Trinity and similar academic updates show 60/40 SWR dropping from around 4% at 30 years to around 3% at 50 years.
For the TAA strategies in our table, expect a similar proportional drop. A 9.7% SWR at 30 years probably becomes something like 7-8% at 50 years. The relative ranking holds (TAA's defensive rotation mechanism gets more valuable over longer horizons, not less), but the absolute numbers come down meaningfully. If you're FIRE planning specifically, mentally derate every SWR in the table above by 20 to 30% before forecasting forward.
2. Half our data starts in the mid-1980s. Bengen's started in 1926.
This is the most important caveat. Bengen's 4% number came from US stock and bond data starting in 1926, which means his rolling 30-year windows included starting points right before the Great Depression (1929 starts ending in 1959, where US stocks fell more than 80% peak to trough by 1932 and a 60/40 portfolio about 63%), and right before the 1973-1981 stagflation (where US stocks lost real value for nearly a decade while bonds got crushed by rising rates).
For half the strategies in the table our data windows start in 1985. That window covers the dot-com bust, the GFC, the 2022 inflation shock, and COVID. It does not cover the Depression, the 1937-38 second crash, or the full 1970s stagflation. The other half reach back into the 1970s (HAA, VAA-G4, the Permanent Portfolio, All Weather) or, for the classic 60/40, to 1922. For the mid-1980s strategies the 30-year rolling windows all start before 1997, so the 2022 shock only reaches the last few years of the latest ones, and none of them include a sustained inflation regime where bonds AND gold AND TIPS all bled together.
For those strategies our SWR numbers are therefore the post-1984 SWR. Adjust expectations downward by 1.5 to 2 percentage points before forecasting forward, because the regime tail risk is real even though our window doesn't see it.
3. SWR is a backtest, not a prediction.
The number "VAA-G4 SmartStack sustained 11.7%" means: in the worst rolling 30-year window of its data (from 1977), that strategy survived an 11.7% real-dollar withdrawal rate. It does not mean future windows will behave the same way. The strategies in our catalog were designed using historical data. Some of their parameters were tuned on the same data the SWR is computed from. There is a non-trivial in-sample-fit component to any SWR computed on a strategy that was published recently.
For long-established portfolios (60/40, Permanent Portfolio) the SWR is closer to an honest out-of-sample number. Even GEM (2014), VAA (2017), BAA (2022) and HAA (2023) were designed on data inside these windows, so their SWRs are partly in-sample too. For the newer SmartStack and SmartLeverage variants (built and published by BestFolio in 2024-2025), the SWR is partially in-sample and should be discounted.
4. SWR doesn't include taxes.
The backtest computes each signal at the close, fills it at that same close and charges an estimated trading cost on every rebalance, but it assumes zero tax. In reality, monthly rotation in a taxable account generates short-term capital gains every month for a TAA strategy. In a tax-deferred account (IRA, 401k), this is fine. In a taxable account, the after-tax SWR is meaningfully lower.
Rough adjustment: a TAA strategy with monthly turnover in a 24% marginal bracket gives up roughly 50 to 150 basis points of CAGR to tax friction depending on the strategy's turnover rate. That same fraction comes off the SWR.
5. The behavioral SWR is lower than the mathematical SWR.
If you set your retirement plan around 12% SWR and the strategy hits its worst regime in year 3 of retirement (delivering, say, the -36.5% drawdown of HAA Leveraged 2x), most people change strategy at the bottom. Selling a TAA strategy in defensive mode locks in the loss and forfeits the recovery rule that the strategy was designed around. The math SWR assumes you hold; the behavioral SWR assumes you behave.
Bengen's 4% number quietly accounts for this. 4% is conservative enough that most retirees don't panic-sell when the portfolio is down 30%, because they know they're nowhere near zero. 12% is not conservative enough. The first three years would be terrifying.
Why TAA strategies sustain higher withdrawal rates
The mechanism is sequence-of-returns risk, and it's worth understanding.
A static portfolio in retirement faces a structural problem. If markets crash in years 1-5, the retiree is selling shares at depressed prices to fund spending, locking in losses. The portfolio never gets the recovery benefit because the shares it would have used to recover got spent. Bengen's 4% number is largely about being conservative enough to survive a bad sequence in years 1-5.
TAA strategies attack this directly. When the trend, momentum, or canary signal flips defensive, the strategy is no longer holding the falling asset. HAA's TIP canary, BAA's 4-asset breadth check, GEM's 12-month relative momentum: all of them rotate the portfolio out of equities (or into a less-risky asset) precisely when the bad sequence is starting. The retiree is now spending out of a defensive sleeve that's roughly flat instead of falling.
Two specific cases from the historical record:
2000-2002 dot-com bust. The Classic 60/40 portfolio drew down 24% peak-to-trough over about 23 months. A retiree withdrawing 6% per year from January 2000 would have ended 2002 at roughly 70% of their starting balance, deep in sequence-risk territory. HAA Standard, by contrast, gained in each of 2000, 2001 and 2002 (about +14% over the three years, against about -14% for the 60/40), although its own deepest drawdown, about 20%, was a sharp drop in March and April 2000 at the top of the bubble. The same 6% withdrawal in HAA leaves the retiree at roughly 95% of starting balance.
2022 inflation + rates shock. Stocks and long bonds both fell, an unusual correlation that wrecked traditional 60/40 portfolios. Classic 60/40 lost 16% on the year. Two of the three SmartStack variants in the table made money in 2022 (HAA SmartStack +5.6%, VAA-G4 SmartStack +2.8%), helped by the managed-futures overlay; ADM SmartStack still lost 20.5%. That single year alone explains a chunk of the SWR gap.
The pattern is consistent: TAA strategies don't necessarily earn more in good years (some do, some don't), but they lose less in bad years. Sequence-of-returns risk is asymmetric, so the strategies that protect downside compound the SWR advantage faster than the math suggests.
The retirement-grade candidates
If you're using this for actual retirement planning, the leveraged variants are off the table. Holding a 2x leveraged strategy in retirement means a 60% drawdown is on the menu, and the behavioral SWR for a 60% drawdown is approximately zero (you'll sell at the bottom).
The three TAA strategies that combine high SWR with bounded drawdowns. Only HAA Standard is unleveraged: the two SmartStack variants hold 2x and 3x funds at partial weights plus a gold and managed-futures overlay, so their exposure runs above 1x (HAA SmartStack peaks at about 1.67x).
- VAA-G4 SmartStack (Gold+MF). 11.7% SWR / -18.8% MaxDD / Sharpe 0.93. The deepest drawdown in its record is a recent one, from February to July 2026, and it had not recovered by mid-October; in 2022 the SmartStack overlay kept the year roughly flat. The shallowest drawdown of any strategy in the table with an SWR above 11%.
- HAA SmartStack (Gold+MF). 9.8% SWR / -22.7% MaxDD / Sharpe 1.05. The highest Sharpe of the three SmartStack rows in the table. TIP canary is a cleaner trigger than VAA's 4-asset breadth in some regimes (faster to flip back risk-on, which captured the 2020 and 2023 rebounds).
- HAA Standard. 10.4% SWR / -19.5% MaxDD / Sharpe 1.10. The vanilla version without the capital-efficient overlay. Easier to implement in a Roth IRA at a US broker (no Avantis-style UCITS gap, no obscure ETFs). On today's cards the SmartStack version has a lower SWR (9.8% vs 10.4%) and a deeper drawdown, so its more complex execution does not buy a higher withdrawal rate here.
Conservative practical recipe for a traditional 30-year retirement: pick one of these as the equity sleeve, hold 10-20% in cash or short-duration Treasuries as a behavioral buffer (you don't have to follow the strategy mechanically in months you don't want to), and target a withdrawal rate around 6 to 7% real. That's still meaningfully above the modern Bengen 4.7% benchmark for 30-year horizons on a multi-cap glidepath, leaves significant margin against the post-1990-window bias, and is psychologically sustainable through a 25-30% drawdown.
For 50-year FIRE planning, derate further. The two SmartStack rates above (9.8% and 11.7%) are closer to 7-9% at a 50-year horizon, and the conservative practical target is around 5 to 6% real. Still well above Bengen's 4% updated benchmark, but the cushion is meaningfully narrower than what the 30-year table implies.
If you want to be fully conservative: take a strategy's 30-year SWR, halve it, then round down. HAA SmartStack at 9.8% becomes 4%. VAA-G4 SmartStack at 11.7% becomes 5%. That's level with or just above Bengen's 4% for 50-year FIRE horizons, with little cushion left for the five caveats above.
What we are not telling you
A short list of additional limitations, in decreasing order of importance.
- Post-1990 bias. Already covered above. Repeated here because it's the biggest issue. Our window misses the worst US regimes for stocks AND bonds simultaneously.
- 30-year rolling windows are overlapping. The roughly 140 windows we get from a 42-year backtest are not 140 independent samples. Neighbouring windows overlap almost entirely. The effective sample size is closer to 5 to 10 truly independent regimes.
- US-only data. Our SWR methodology uses US CPI for inflation. A European or Japanese investor faces different inflation realizations and currency exposure. The SWR for the same strategy held in EUR or JPY is meaningfully different.
- In-sample fit for newer strategies. The SmartStack and SmartLeverage variants were designed in 2024-2025 using data the SWR is now backtested on. There is unavoidable curve-fit risk in any newly-published strategy.
- Bengen used SAFEMAX with explicit failure on the worst window. So do we. But we use binary search to find the rate; in extreme cases the binary search can converge to a number that's exactly the worst-window rate with no margin. Add 50 to 100 basis points of safety margin to any cited SWR.
- CAPE valuation adjustment. Bengen's updated framework includes a CAPE-based adjustment: when starting valuations are high (as they are in 2026), the safe withdrawal rate should be derated. Our analysis does not account for this. The implied derate at current CAPE levels is in the 50-100 basis point range relative to a long-run average starting CAPE.
- Single-asset failure modes. If a TAA strategy holds 100% TLT in a defensive month and TLT loses 7% that month (like several months in 2022), the strategy bleeds. The diversified SmartStack variants are more robust to this than the binary canary strategies because the defensive position still has a managed-futures overlay rather than concentrating in one bond ETF.
Practical takeaway
The 4% rule is conservative for almost every strategy in the BestFolio catalog. That's the actual finding. The 4% rule is also probably the right number to use anyway, for behavioral reasons and for regime-tail-risk reasons that our data windows, half of which start in the mid-1980s, can't see.
The genuinely useful takeaway is that the gap between strategies is enormous. A retiree holding Permanent Portfolio (5.4% SWR) versus HAA SmartStack (9.8% SWR) has very different headroom against bad sequences. They both clear the Bengen number, but one can withdraw nearly twice as much as the other for the same retirement horizon. That matters whether you withdraw 4% or 6% or 8%.
If you want to see the SWR for any specific strategy in your portfolio, the BestFolio strategy detail pages now show it alongside CAGR, MaxDD, and Sharpe. Browse the catalog or build a custom portfolio and the engine computes the rolling-window SWR on the blended NAV directly.
All numbers in this post come from BestFolio's backtest engine on production data, computed via rolling-window Bengen methodology with real US CPI from the FRED API. Data windows start between 1922 and 1985 depending on strategy and run to October 2026; figures restated on 8 October 2026, the Quartet row on 13 October, the managed-futures rows on 15 October and the rows with international or emerging-market stocks on 16 October 2026; Sharpe ratios, now measured above cash, on 18 October 2026. The methodology source is at backend/app/services/withdrawal_rate.py if you want to inspect the algorithm directly.