Two of my favorite ideas in investing pull in the same direction, and almost nobody runs them together. HAA gives you a momentum rule with a built-in exit. Return stacking gives you leverage without margin. Bolt them together and you get one sleeve that carries the leverage and the exit at the same time. This is the version I actually run, plus the UCITS build I put together for the EU side the moment someone asked.
The two ideas
HAA is Wouter Keller and Jan Willem Keuning's Hybrid Asset Allocation. It holds an offensive sleeve while momentum is positive, and it watches a canary to decide when to step aside. The momentum measure is the 13612 score, an average of the 1, 3, 6 and 12 month total returns, read on month-end data and acted on once a month. The canary is TIPS, so really inflation and rates: when TIP's 13612 turns negative, the whole thing moves to the defensive side, intermediate treasuries or T-bills. It's one of the cleaner crash rules out there, and it nailed 2022 by sitting in cash for most of the year.
RSST is Return Stacked US Stocks & Managed Futures. One ticker gives you roughly 100% S&P 500 plus 100% managed futures, so about 2x notional with no margin in your account. The trend overlay rides on top of the equity without tying up extra capital. It is not free: the fund's fee and the cost of financing the extra futures exposure come out of the return, and the backtest charges both. That's the whole idea of return stacking: you stop giving up your equity just to hold a diversifier.
And that second point is the real game. RCM Alternatives had a good piece recently on how the hardest trade is holding the thing that doesn't hug you back. Managed futures spends years being boring or annoying, and most people bail right before it pays. Return stacking removes the choice. You hold the S&P and the trend sleeve together, rather than picking one.
The blend
Take textbook HAA-Simple and swap the offensive asset from plain SPY to RSST. That's the only change. Everything else is straight Keller and Keuning.
When the canary is risk-on and SPY's own momentum is positive, I'm effectively 100% RSST, so about 100% S&P plus 100% managed futures. When it flips risk-off, I head to the defensive side, intermediate treasuries or T-bills depending on which has the better momentum at the flip. In a rising-rate mess like 2022, that meant bills. One position, rotated once a month.
Return stacking hands you the leverage. The canary hands you the exit. Two ideas that were great on their own, way better bolted together.
The numbers
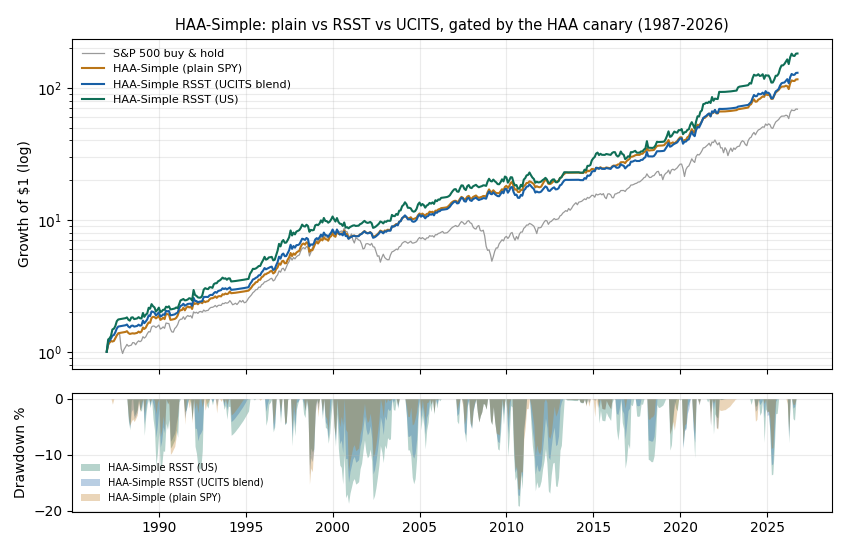
Around 17% CAGR over the long backtest, max drawdown in the low 20s% on daily closes, Sharpe near 1.2. I rebuilt it three times because I flat out didn't believe the drawdown the first time...
Here's the head to head: the US RSST version, the UCITS build I'll get to next, the unaltered HAA-Simple (plain SPY, no return stacking), and a plain S&P.
| Metric | US RSST | UCITS blend | Plain HAA-Simple | S&P 500 |
|---|---|---|---|---|
| CAGR (1987 to 2026, reconstructed) | ~14% | ~13% | ~13% | ~11% |
| Max drawdown (month-end) | -19% | -18% | -16% | -51% |
| Sharpe | 1.0 | 1.1 | 1.2 | 0.8 |
| CAGR (live, since 2019) | ~22% | ~19% | ~16% | n/a |
| Sharpe (live, since 2019) | 1.35 | 1.42 | 1.40 | n/a |
Plain HAA-Simple is the calmest of the bunch, the best long-run Sharpe and the shallowest drawdown. RSST and the UCITS blend buy extra return for a little more drawdown, and most of that edge shows up on the live window since 2019, when managed futures actually did its job.
A few honest notes, because this stuff matters:
- RSST is only a couple of years old, so the deep history is reconstructed: synthetic managed futures stacked on the S&P, with the trend leg modeled back to the 1980s off a managed-futures index. Weight that reconstructed era heavily and the figure is mid-teens, not 17, so trust the shape more than the exact number. The live window since 2019 has run hotter, low-20s, but it's a tiny sample, and RSST itself only launched in September 2023.
- The canary watches inflation and rates, not equity drawdowns. So it sat out 2022 beautifully, but in 2008 it only flipped in September; SPY's own momentum had already moved the strategy into treasuries in January. It's not a fast-crash dodger.
- Costs are in there, 10 bps a side on turnover. Sharpe uses a zero risk-free rate, so the levered figures stay comparable to plain HAA.
The UCITS problem
I shared this on r/LETFs and the very first reply was basically "you get me as a customer the day this works with UCITS." Fair enough. So I built it.
Here's the catch. There's no clean UCITS version of RSST. Nothing on this side of the Atlantic stacks stocks and managed futures in one wrapper. Return Stacked were working on a European launch and then shelved it, which I only knew because a commenter had emailed them and got the bad news straight from the source.
So, can you get close? You can, with two pieces:
- A 2x S&P 500 UCITS ETF (the Xtrackers swap-based one, for example) for the equity.
- DBMF, the iMGP DBi Managed Futures UCITS ETF, for the trend sleeve. It's the one proper managed-futures ETF Europe has.
The snag is leverage. DBMF is 1x, and there is no leveraged managed-futures UCITS, so you can't rebuild RSST's full 100/100. The move is to lever the equity instead, to free up cash for the futures. Roughly 50% in the 2x S&P plus 50% in DBMF gets you about 100% S&P and 50% managed futures. Half the trend stack of real RSST, but about as close as you get over here...
How the UCITS version backtests
I ran the UCITS blend through the exact same HAA canary and put it head to head with the US version. For the deep history I model the 2x leg on a calibrated daily-leverage series (the same machinery that reproduces real leveraged ETFs to within a fraction of a point a year) and the managed-futures leg on DBMF, carried back through the same index RSST uses.
Over the long backtest it trails by 1 to 2 points of CAGR. Two reasons. The lighter trend sleeve, 50% against 100%. And a structural cost the US version dodges: RSST holds its S&P at plain 1x and stacks the futures as an overlay, so it pays no daily-reset decay on the equity, while the UCITS build reaches 100% equity through a 2x daily ETF, which bleeds a little in choppy markets.
And here's the nice surprise. The drawdown comes out a hair shallower and the Sharpe a little higher. You trade away some raw return for the wrapper, almost nothing risk-adjusted. On the live window since 2019, the US version earns more, about 22% a year against 19%, but the UCITS version's Sharpe actually edges ahead on lower vol. Not all of that is real fund history, though. RSST only launched in September 2023, the DBMF UCITS ETF in March 2025.
One quiet reason it holds up so well: the canary does the heavy lifting on protection, not the trend sleeve. So running half the managed futures hurts less than you'd fear, because you're usually out of the offensive sleeve during the exact regimes where trend would have mattered most.
Where it lives
Both versions are on BestFolio now, as variants of HAA: the US one and the UCITS one. The canary and the monthly rotation run for you, so it's a once-a-month check rather than a manual rebuild every signal.
Same honest framing. This is a high-octane satellite, not a core. Reconstructed history, a canary that is slow on pure equity crashes, real drawdowns in the low 20s. But the core idea, stop paying for your diversifier in lost equity, and stop holding it through the regimes where it just bleeds, is one of the better things I've put in a portfolio in a long time.